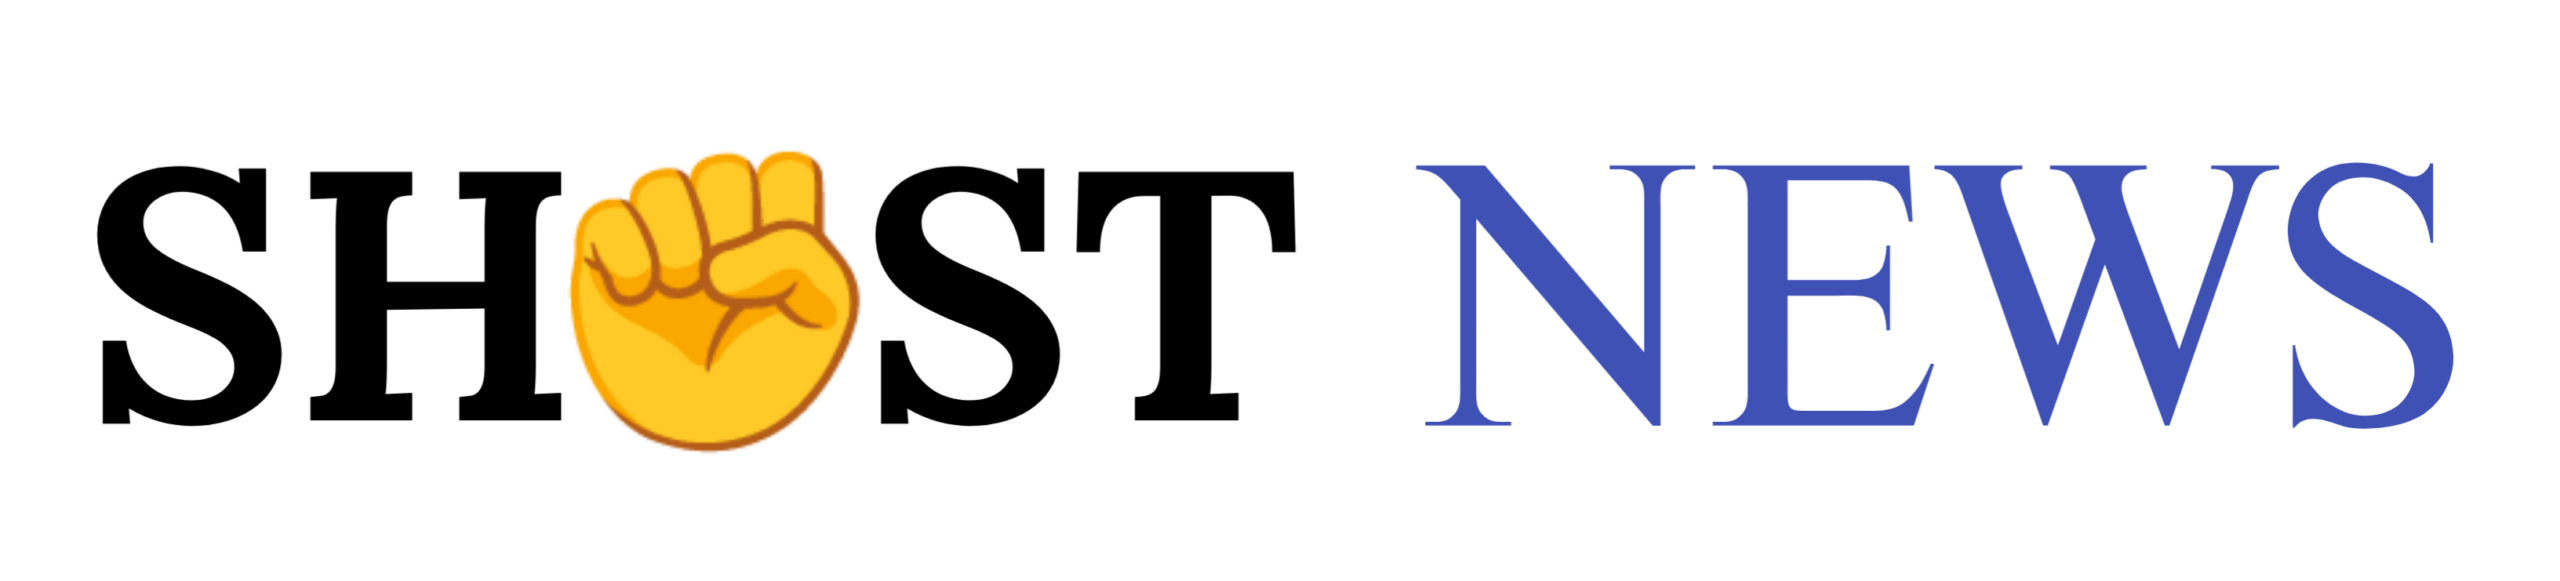
Nigeria needs significantly more productive investment if the country is to create enough jobs for its rapidly growing population, the Nigerian Economic Summit Group has warned. The organisation said investment remains critical to expanding businesses, increasing productivity and generating employment opportunities.
The warning comes as millions of Nigerians continue to search for employment opportunities while businesses face high operating costs. According to the NESG, attracting investment must go beyond economic figures and should result in the expansion of businesses, infrastructure and productive industries. The organisation has highlighted issues such as infrastructure, access to long-term financing, electricity, regulatory uncertainty and the general cost of doing business as important factors affecting investment. Nigeria has a large and youthful population, meaning millions of people enter the labour market every year. This creates pressure on the economy to produce enough jobs and business opportunities to accommodate the growing workforce. The NESG has therefore continued to push for policies that encourage private investment and strengthen the productive sectors of the economy.
The organisation is also expected to focus on investment and job creation during its upcoming Nigerian Economic Summit. The government has introduced several economic reforms aimed at improving the investment environment, but businesses and investors will ultimately look at whether those reforms produce a more predictable and productive operating environment. For Nigeria, the challenge is not simply attracting money into the country. The bigger issue is ensuring that investments are directed towards industries capable of creating jobs, increasing production and improving living standards. The latest warning from the NESG therefore places investment at the centre of Nigeria’s continuing conversation about employment and economic growth.
Similar Posts
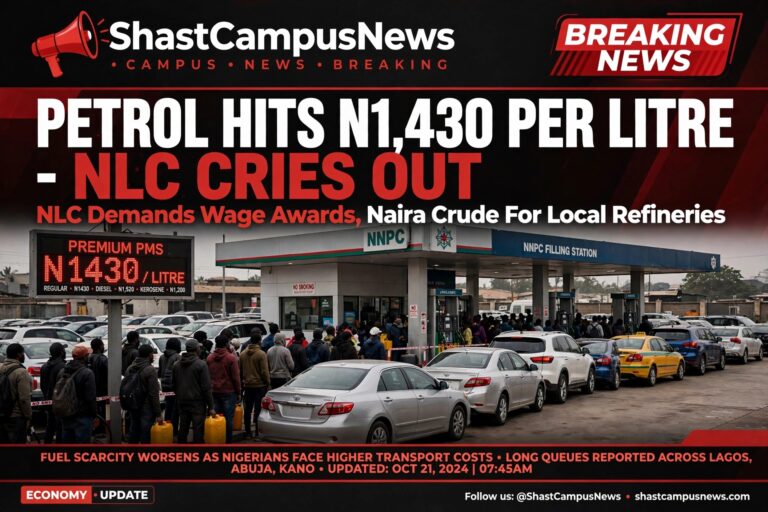
Petrol Price Hits ₦1,430 as NLC Demands Wage Awards and Emergency Relief
The rising cost of petrol has triggered fresh concerns across Nigeria, with the Nigeria Labour Congress (NLC) calling on the Federal Government to urgently intervene as petrol prices climb to about ₦1,430 per litre in some major cities. The labour union says the increase is placing additional pressure on workers and households already struggling with…
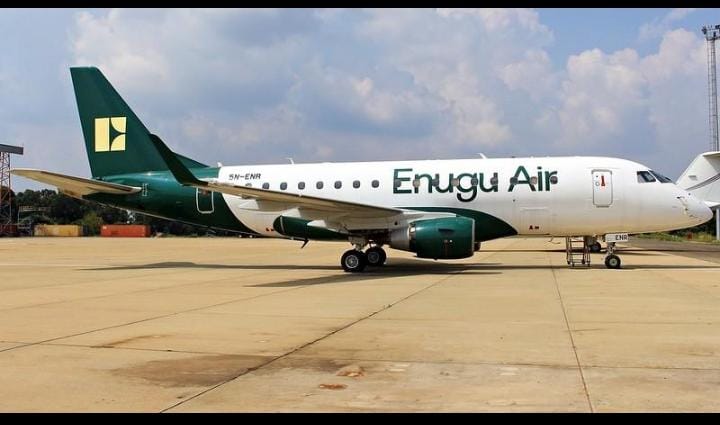
Enugu Air Set to Launch Direct Enugu–Douala Flights September 23
Enugu Air is set to begin its first international route on September 23, connecting Enugu directly with Douala, Cameroon, in a move that will expand the airline’s operations beyond Nigeria. The new route will connect Akanu Ibiam International Airport in Enugu with Douala International Airport, creating a direct air link between southeastern Nigeria and Cameroon….
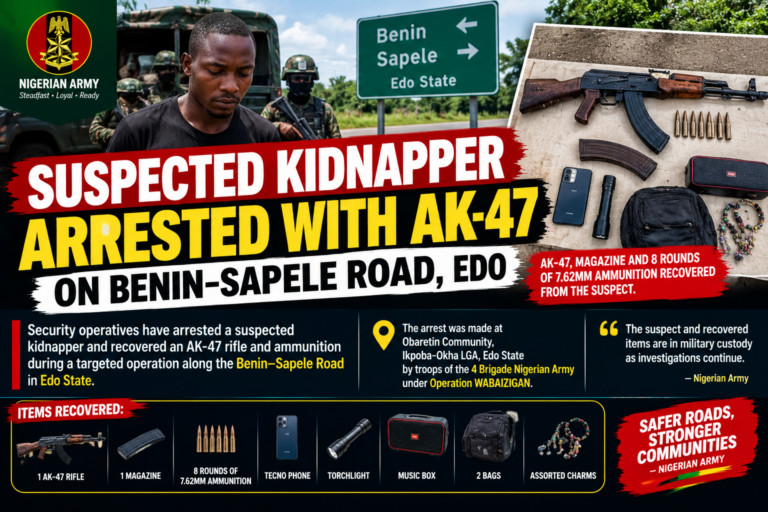
Suspected Kidnapper Arrested With AK-47 on Benin–Sapele Road in Edo
Security operatives have arrested a suspected kidnapper and recovered an AK-47 rifle and ammunition during a targeted operation along the Benin–Sapele Road in Edo State. The suspect, identified as Olamide Oyeniyi, was arrested on September 12, 2026, at Obaretin Community in Ikpoba-Okha Local Government Area by troops of the 4 Brigade Nigerian Army operating under…
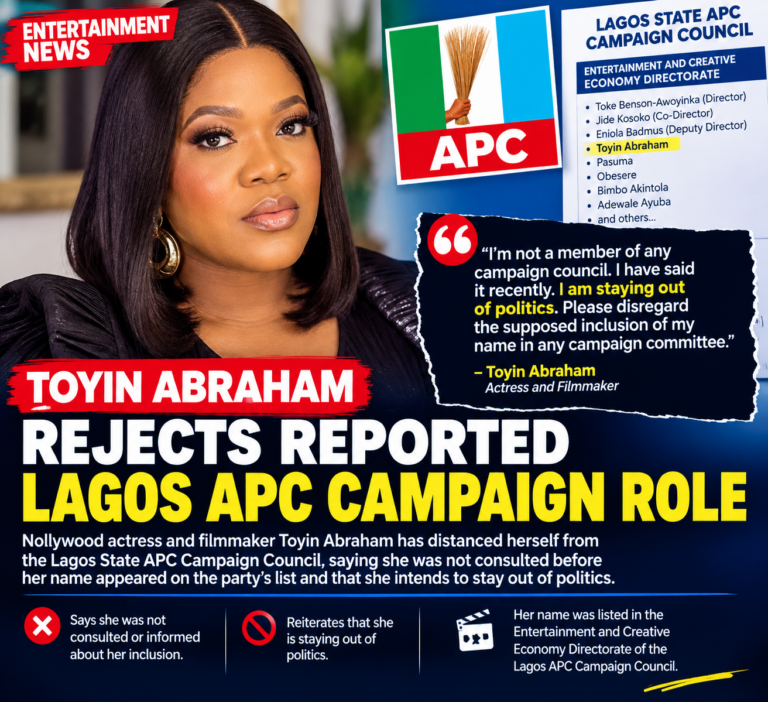
Toyin Abraham Rejects Reported Lagos APC Campaign Council Role
Nollywood actress and filmmaker Toyin Abraham has distanced herself from the Lagos State All Progressives Congress (APC) Campaign Council after her name appeared among entertainment personalities listed in the party’s campaign structure. Abraham’s name was included in the Entertainment and Creative Economy Directorate, alongside prominent figures including Jide Kosoko, Eniola Badmus, Bimbo Akintola, Pasuma, Obesere…
More Than 80 Reportedly Abducted as Fresh Security Incidents Raise Concern Across Nigeria
Fresh reports of abductions in parts of northern Nigeria, alongside the discovery of suspected human remains in a separate police operation in Abia State, have renewed attention on the country’s security challenges. More than 80 people, including farmers and women, were reportedly abducted in separate incidents in Niger and Zamfara states, according to reports published…
Nigeria, US Sign Mineral Investment Pact as FG Moves to Expand Critical Minerals Sector
Nigeria and the United States have signed a framework agreement aimed at deepening cooperation and investment in Nigeria’s solid minerals sector. The agreement was signed on the sidelines of the 81st United Nations General Assembly in New York. Minister of Solid Minerals Development, Dele Alake, described the framework as a future-focused arrangement designed to strengthen…